Get Pre Approved
How To Qualify For a Mortgage
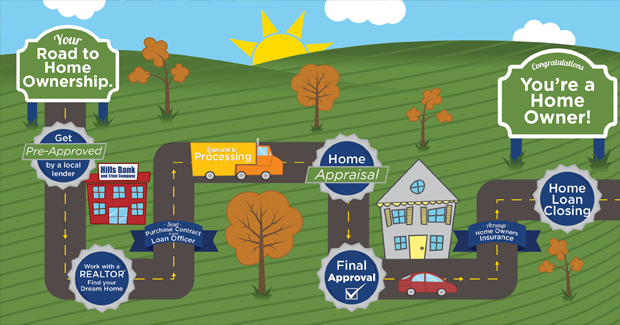
As you start the mortgage application process, your mortgage loan lender/broker will require that you provide the following information:
- Employment and Income. This includes paystubs, W-2s or 1099s, and proof of income. Your income will determine the type of loan and the amount the lender will lend you.
- Credit Score. Your loan originator will ask your permission to view your credit score. Typically, you need a credit score of 640 or higher for a home loan, but some lenders and loan types will allow a lower credit score. If your credit is in need of repair, a loan officer can provide you with free advice on how to repair your credit score. Working with a good local mortgage broker can make all the difference in the world. We highly recommend working with a local mortgage broker not a lender or online lender.
- Assets and Cash Reserves. This can be found on your bank statements and investment account statements. Your lender will want to know what assets you own and if you have any cash saved. It is okay if you do not.
- Debt-to-Income Ratio (DTI): DTI is your total monthly expenses divided by your total monthly income before taxes. Lenders will calculate this to determine if you’ll have the funds to repay the loan. Lenders typically require a DTI from 36% to 43%. The question the lender will be looking to answer is
- Property Type. The type of property you plan to purchase, such as a single-family home, multifamily, condominium, co-op, or manufactured home will determine your eligibility to buy. The loan type and the amount you qualify for will determine your eligibility to purchase various types of real estate.
- Down Payment. This is the amount of money that a homebuyer or property buyer “puts down” to secure the loan or reduce their interest rate. Typically the more you put down the lower your interest rate ue to the type of loan you qualify for but there are home loans available to Mississippi homebuyers that require $0 down or as little as 3.5% down. Example: 3.5% down to purchase a $230,000 home is $8,050
- Home Appraisal. Your lender will require that you hire an appraiser to determine the market value of the home. If the home does not appraise for the price you offer to the seller, the seller will have to reduce their price, or you will have to put down more funds for the loan to close. If you cannot put down more funds and the seller will not reduce their price, the contract will be voided.
- Home and Flood Insurance. The cost of insurance can greatly decrease the affordability of a home by increasing the monthly cost to purchase a property and may keep you from qualifying to purchase the property.
- Mortgage Insurance. Conventional loans with less than 20% down require PMI be paid as part of the monthly mortgage payment to protect the lender if the borrower fails to repay the loan. With a down payment of 20% lenders won’t charge PMI on a new mortgage.
Click Here to get pre approved right away.
Important Homebuying Tips
View Properties That Fit Your Budget
Everyone hates to waste time, and spending hours or days viewing homes that don’t fit within your budget is not only a waste of time, but it can be a huge disappointment. Finding out that you can’t qualify for the home you have your heart set on can be a real letdown. On the other hand, if you are able to qualify for more than what you think, you may be selling yourself short and settling for something that isn’t quite what you want. This is one reason why it is important to get preapproved for a loan before you begin your home search. Another reason to get preapproved first is that many sellers in today’s market will not allow buyers who have not been pre-approved to view their home. Most homes on the market today are owner occupied and homeowners do not want to reschedule their daily lives around buyers who are “just looking”. In the eyes of many sellers, a buyer who hasn’t taken the most important initial step in the purchase process, probably isn’t serious. Today’s sellers are also aware that there are criminals who pose as buyers and will use showings as an opportunity to “scout out” things like the level of security, types of valuables in a home and the presence of a guard dog. It’s an ugly truth, but many wary home sellers are being more cautious, and want assurance before they will let just anyone enter their home. Obtaining a letter of pre-approval from a lender will go a long way towards that end and also ensure there isn’t a delay when you are ready to view a home you’re interested in seeing.
View Properties You Love
Make a list of what is most important to you. Write down the attributes of your future home and stick to your list. Do you need a big backyard? Four bedrooms? Single story home? Make sure you know what is most important to you before you start your search. We also recommend, if you can, riding around the neighborhood of homes you are interested in prior to viewing them. The neighbors of a property are just as important as the house itself.
Make An Offer Quickly
Most sellers will require a buyer to produce a pre-approval letter before any offer will be accepted. We have often found ourselves working with buyers who find the “perfect home” but their offer isn’t taken seriously or accepted due to a lack of preparation AKA not having their pre-approval ready. We have seen clients miss out on homes they have fallen in love with because another buyer who has a pre-approval makes an offer while our client waits to get theirs. In other cases, we have seen buyers get stuck awaiting pre-approval, leading to a multiple offer situation. A lack of preparation can cost you valuable time and allow other buyers to view and present an offer while you are forced to wait…
Be Comfortable With The Payment
A lender can give you a very close estimate of what your monthly payment will be depending on several different factors, such as the loan amount, loan type, your credit score, interest rate, insurance cost and the amount of years you finance the home.
Choosing A Lender
Click Here to get pre approved right away.
No matter if you’re a first-time home buyer or if you’re buying your 100th property, choosing the right lender is one of the most important steps of the home-buying process. Not only are comparing rates and lender fees extremely important, but finding a local mortgage broker who understands the nuances of buying a home on the MS Gulf Coast can make all the difference in your experience and whether or not you get the home you want.
Many if not most banks and credit unions are considerably slower when it comes to the closing process and good luck getting one of them to answer the phone after hours or over the weekend. Once you are under contract, there are many tight deadlines to meet throughout the contract. It is in your best interest to hire someone who is motivated to meet those deadlines in a timely manner or your closing process is likely to be much more stressful than it needs to be or you could lose the home of your dreams due to missing important deadlines. The biggest difference between a bank’s mortgage lender and a local mortgage broker is a lender gets paid hourly no matter if your home loan closes and a mortgage broker has a higher education and only gets paid if your home loan closes.
In our experience, even clients with longstanding banking relationships have frequently received poor service and are displeased with their bank by the end of the transaction. Feel free to ask us for more details or follow the link for our approved vendor list. We are happy to get you going in the right direction!
Testimonials
"
Brittany Geotes is a very resourceful realtor with a keen eye for value and quality. Britt marketed a property that I owned and sold it within hours of placing it on the market. Britt also has been my realtor on a new home purchase. Her connections and professionalism are immeasurable. I am equally impressed with her level of communication. Britt made sure I was well informed as information came available and always returned my calls and texts in minimal time. If you are looking for a realtor that will work diligently for you, Britt is your girl. I’ve purchased and sold several properties in 25 years and she is my top realtor.
"
- Christopher Andersen
"
Tara Wallace was our real estate agent. She helped us buy a place in Bay St. Louis. She was very professional and so knowledgeable about the whole process. She replied immediately to our calls, texts and emails. She helped us getting companies for our inspection and our insurance. She was extremely helpful and made our experience go very smoothly. I would highly recommend Tara to anyone looking to buy or sell property in South Mississippi.
"
- Donna Tehas
"
Laken Scarborough is the absolute best! She always goes above and beyond for all of her clients and truly helps to make dreams become a reality. She has an amazing down-to-earth personality and is extremely quick to answer any questions!
"
- Megan Clark
"
Jenny is amazing! She made buying a breeze! She always answered my text right away and if she didn’t have an answer she found out super quick. She was great at helping us negotiate and got us what we were hoping. Highly recommend!!
"
- Lacy Belue
"
After 3 years of looking and Deborah’s consistency, I finally found the house that checked all the boxes. From the moment I saw it until the day I moved in was about 45 days. Deborah goes the extra mile in every way; availability, providing local information for needed repairs, loan officers and she even took a trip to the hardware store and purchased some items to help close the sale at the last minute. You can not ask for more in a realtor. Deborah goes above and beyond in every way. Thanks Deborah for helping make a lifelong dream of owning a family home in a great community a reality.
Jacob
"
- Jacob L.
"
If you want an easy home buying experience, use this team!!! They are professional, responsive, have great connections, and they care! All realtors are not the same. I have used many realtors in the past but my experience with two different agents at this company exceeded expectations.
"
- Don Moore
"
Kathy Serpas was a God send. Her perseverance and dedication to helping me buy my home during a pandemic made my home buying experience wonderful. Not being from Mississippi Kathy's knowledge of the area put my mind at ease. I highly recommend Kathy to anyone ready to buy or sell a home. Thanks again Kathy.
"
- Lela Dunklin
"
Harim did a phenomenal job. He was patient, knowledgeable, thorough, and honest. He was truly a Godsend and helped us find a beautiful home. He went above and beyond to answer our questions and resolve any issues that arose. We couldn’t have asked for or found a better agent. We highly recommend Harim Yanes as your realtor.
"
- Jay and Tracie Evers
"
Brittany is so wonderful to work with! It’s always great to work with someone that loves what they do. She has a way of making things easier to deal with and you will feel like you’ve known her forever!
"
- Emily Hughes (Director of Operations)
"
I have worked with NextHome Simplicity agents for almost 5 years as a home stager and it has been a real pleasure. They are consummate professionals, talented individuals that work hard for their clients. I highly recommend them for any real estate need.
"
- Chris Forbes
"
I received an email this morning to write a recommendation for Andrew Geotes. I sat at my desk for a minutes thinking to myself how do I write this recommendation without coming across cheesy and appear to be a fake review. I wished I could tell you about these things in person, not only to hear my words but see the excitement and gratitude that I have for Andrew and Kathy at Next Home Simplicity. My wife and I were unsure if we wanted to sell our house. We heard from close friends that today’s market was the time to sell. We loved our home, maybe we just don’t need the stress right now in selling and buying a new home. We called Andrew and met with him at our home. The first words he said to us, have you picked a house you’re ready to buy. This shocked us. He said this is a hot market, but your house is beautiful. It will sell in a day or so once we listed it. We wondered the validity of this. In any facet of our lives, we hear over commitments and are delivered under performance. Well, those fears, and anxieties were washed away with Andrew and Kathy. We just met these two and felt like we were important to them. Honestly Andrew and Kathy made us feel like we were family to them. This approach, this professionalism remained throughout the course of selling, buying and after the transaction. I can honestly say, if you want a realtor that goes above and beyond your expectations that team is with Next Home Simplicity. I know deep in my heart your home and future home will be handled the same manner. You will not be disappointed. There is nothing worse than be under served and under performed by folks you put trust in. You will not feel this way with Andrew and Kathy. I honestly wished Andrew and Kathy could teach this to so many professionals we deal with in our lives. I know we all have had professionals in our life that it felt they were doing us a favor versus doing their jobs. Almost all of us buy or sell a home 2 or 3 times in our lives, make sure you pick someone to make those times exciting and stress free. Andrew, Kathy, and the team at Next Home Simplicity will ensure you are satisfied with every step throughout the process.
Thank you
Kristin
"
- Kristin Helman
"
Paul is one of those rare finds in the world of Realtors. He has the knowledge & expertise to ensure your home purchase closes smoothly, on time & with accuracy. Add to that, his personal touch which creates the experience of working with a friend. I will use & recommend Paul to everyone. From helping us find homeowner insurance, a new roof & title company, Paul is more than just a Realtor he was a recourse.
"
- Phillip T Abromitis
"
Brittany was very professional. She made herself available after hours for questions and concerns. She went out of her way to help us find the right house and made the process smooth. Brittany made us feel like we were a priority. I would recommend her to anyone looking for a home on Mississippi coast.
"
- Susan Dasher
"
What an unusual and amazing experience I just had with April Cummins. First of all, I never met her in person, or set foot in the condo that I bought until days before closing. That is how much I trusted April. We mostly spoke via texts and emails because I was in Boston MA and she was in Diamondhead MS. We have reams of emails and texts where she kept me in the loop every step of the way. She walked me through every move and was the most honest and delightful realtor I have ever dealt with. I can not wait to settle in my new condo and meet her for a hug! She is the best!
"
- Elizabeth A Wallace
"
Ken was awesome! He created a beautiful listing description of my house with rare attention to all details. His "team" quickly staged my home, created outstanding photography, and presented a state-of-the-art virtual tour for potential buyers. He involved himself wholeheartedly in each of those tasks, paying careful attention to my desires, needs, questions, and concerns. I am very familiar with agent practices in Atlanta and in Los Angeles. I found his "cutting edge" approach to be outstanding! His expertise in valuing my home created a big added profit for me. We became great friends; he even came over to help me when I was packing to move! Thanks Ken ...you are a real GIFT in this industry! By the way , Ken gets all the credit for selling the house in 1 day!
"
- Kathleen Gremillion
"
Brittany is awesome! So professional and knowledgeable, truly amazing at what she does!
"
- Marlene Woodings
"
It was a stressful, rough and a long process!
Brittany, is a go getter and will get the job done! Thank you, Brittany for helping us get our house sold! We appreciate it and all the hard work!
"
- Rachel
"
If you're looking for a realtor, I would highly recommend Miss Jena Regan. Whenever I call, texted, or emailed, she was very prompt to get back to me and have the answers I needed. She is very knowledgeable and will not disappoint you. I would definitely use her again.
"
- Ralph Domio
"
If you want someone that will go above and beyond for you then ask for LaQuisha Arbuthnot. She’s amazing! Always professional and very knowledgeable in the business. Thank you for providing me with great information on my journey to find a perfect home.
"
- Shani Williams
"
Brittany is so incredibly helpful and insightful. She listens to you and understands exactly what you are looking for and DELIVERS! Cannot recommend her highly enough
"
- Emily Thevis (Physician Liaison)
 MLS United® - All information deemed reliable but not guaranteed. All properties are subject to prior sale, change, or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
